Solar for Small Business: Tax Deductions and Depreciation
Unlock the tax benefits of commercial solar. Call (833)-212-3715 to speak with a specialist about solar for small business tax deductions and depreciation.
By Alexia Mabel
Learn more about Solar Panel Installation and Repair for guides, costs, and what to expect.
Compare Solar Panel Installation and Repair Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
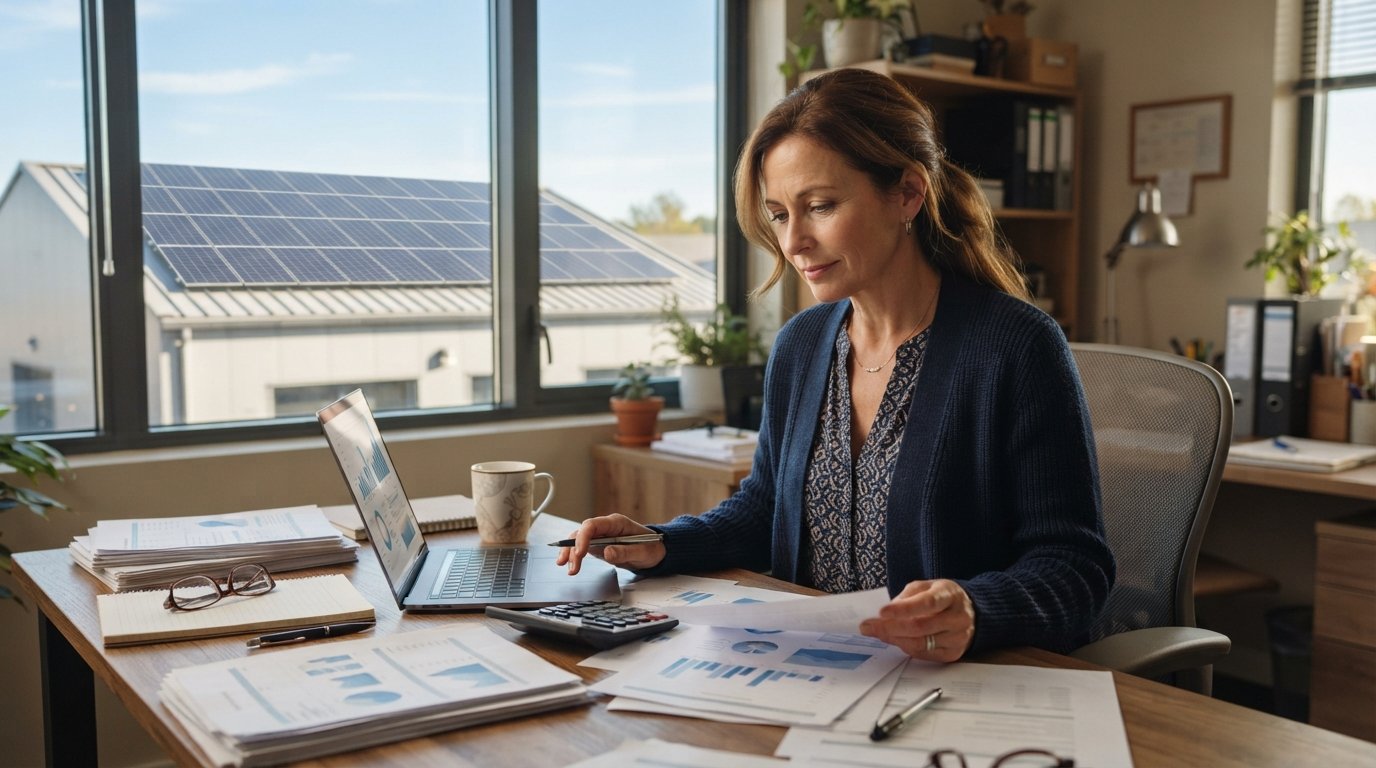
For small business owners, the decision to go solar is often driven by two powerful forces: the desire to slash operating costs and the opportunity to make a smart, tax-advantaged investment. While the environmental benefits are clear, the financial case hinges on understanding the complex web of federal tax credits, accelerated depreciation schedules, and state-level incentives. Without a clear roadmap, it is easy to leave money on the table or miss critical deadlines. This guide breaks down exactly how solar for small business tax deductions and depreciation works, so you can maximize your return on investment and turn your energy strategy into a financial win.
Federal Tax Credit Eligibility for Businesses
The cornerstone of any commercial solar investment is the federal Investment Tax Credit (ITC). For projects commenced in 2026, the ITC allows businesses to claim a credit equal to 30% of the total installed cost of the solar system. This is a dollar-for-dollar reduction of your federal tax liability, not just a deduction from taxable income. If your business owes $30,000 in federal taxes and your solar system costs $100,000, the ITC wipes out that $30,000 bill entirely. Any unused credit can typically be carried forward to future tax years, providing flexibility for businesses with fluctuating profits.
To qualify, the system must be installed on property you own or lease (with certain ownership structures) and must be used for business purposes. The credit applies to the entire cost of the system, including panels, inverters, mounting hardware, labor, and necessary electrical upgrades. However, if you finance the system with a lease or a power purchase agreement (PPA), the third-party owner claims the ITC, not you. For small businesses looking to capture the full tax benefit, direct ownership (purchasing with cash or a loan) is usually the most advantageous route. It is also important to note that the ITC begins to step down after 2032, so acting sooner guarantees the highest credit rate.
Accelerated Depreciation and Bonus Depreciation Rules
Beyond the ITC, depreciation is the second major tax lever for commercial solar. The IRS allows you to depreciate the system over a set schedule, but thanks to the Modified Accelerated Cost Recovery System (MACRS), solar assets qualify for a 5-year recovery period. This means you can deduct the cost of the system from your taxable income much faster than the panels actually wear out. But the real power comes from bonus depreciation, which lets you deduct a large percentage of the system's cost in the first year.
Under current rules (as of 2026), bonus depreciation is scheduled to phase down: 40% for 2025, 20% for 2026, and 0% thereafter for most property. However, solar energy property has historically been eligible for 100% bonus depreciation when placed in service before 2023, and subsequent legislation may extend or modify these rules. For planning purposes, assume you can claim a substantial first-year deduction. Combined with the ITC, this can drastically reduce your tax bill in the year the system is installed. For example, a $100,000 system might generate a $30,000 ITC and a first-year depreciation deduction of $20,000 (20% bonus) plus regular MACRS depreciation, creating a powerful one-two punch.
Interaction with State Incentives and Utility Rebates
Federal benefits are just the beginning. Many states offer additional tax incentives, rebates, or grants for commercial solar. These can include state tax credits (e.g., in New York or California), property tax exemptions (keeping the added value of solar off your property tax assessment), and sales tax exemptions on equipment. Utility companies may also provide rebates based on system size or performance. However, there is a catch: the IRS requires you to subtract any cash rebates or grants you receive from the system's cost basis before calculating the ITC and depreciation. In other words, if you get a $10,000 rebate on a $100,000 system, your federal tax basis becomes $90,000, and your ITC is 30% of that ($27,000). State tax credits, on the other hand, may not reduce your federal basis, depending on how they are structured, so it is crucial to consult a tax professional.
For small businesses, stacking these incentives can dramatically shorten the payback period. In states with strong programs, the combined federal and state benefits can cover 50% or more of the system cost. That is why understanding the local landscape is essential. Our guide on solar for small homes system sizing explains how system size affects savings, a principle that applies equally to small businesses evaluating their energy needs.
Documentation and Planning Steps Before Signing a Contract
To claim these tax benefits, you need a solid paper trail. Before you sign any contract, gather the following documents and information. This checklist will help you avoid surprises at tax time and ensure you capture every eligible deduction.
- Detailed Invoice and Contract: Ensure the contract breaks out equipment costs, labor, permits, and any add-ons. The IRS requires a clear cost basis for the system.
- Proof of Payment: Keep records of all payments, including financing agreements. If you use a loan, you will need documentation showing the system is owned by your business.
- Utility Rebate Letters: If you receive a rebate, retain the award letter and documentation showing the amount, as this reduces your federal tax basis.
- State Incentive Paperwork: Apply for state credits or exemptions early, as some programs have caps or deadlines. Keep copies of approvals.
- Depreciation Schedule: Work with your CPA to determine the optimal depreciation method (MACRS with bonus depreciation) and to calculate the first-year deduction.
Additionally, consider the timing of your installation. The tax credit and depreciation are claimed in the year the system is placed in service, not the year you sign the contract. If you want to capture the 30% ITC and any remaining bonus depreciation, plan to have the system fully operational before December 31 of the desired tax year. Finally, if you are relocating your business or expanding to a new facility, resources like Moving.Homes offer practical checklists for managing the logistics of a move, which can help you coordinate a solar installation at your new location.
Maximizing Your Return: Combining Tax Strategies
The most successful small business solar projects treat tax planning as an integral part of the investment decision, not an afterthought. By combining the ITC, accelerated depreciation, and state incentives, you can often achieve a payback period of five to seven years, after which the electricity is essentially free. However, every business has a unique tax situation. A profitable business with a large tax appetite may benefit more from bonus depreciation, while a startup with lower initial profits might prefer to carry forward the ITC. It is also worth exploring whether your business can monetize the ITC through tax equity arrangements, though these are typically more common for larger projects.
To ensure you are not missing any deductions, schedule a meeting with a tax advisor who specializes in renewable energy. They can model different scenarios, including the impact of the phase-down of bonus depreciation and the interaction with the Alternative Minimum Tax (AMT). With the right approach, solar for small business tax deductions and depreciation can transform a capital expense into a strategic financial advantage, lowering your tax bill while locking in predictable energy costs for decades to come.