
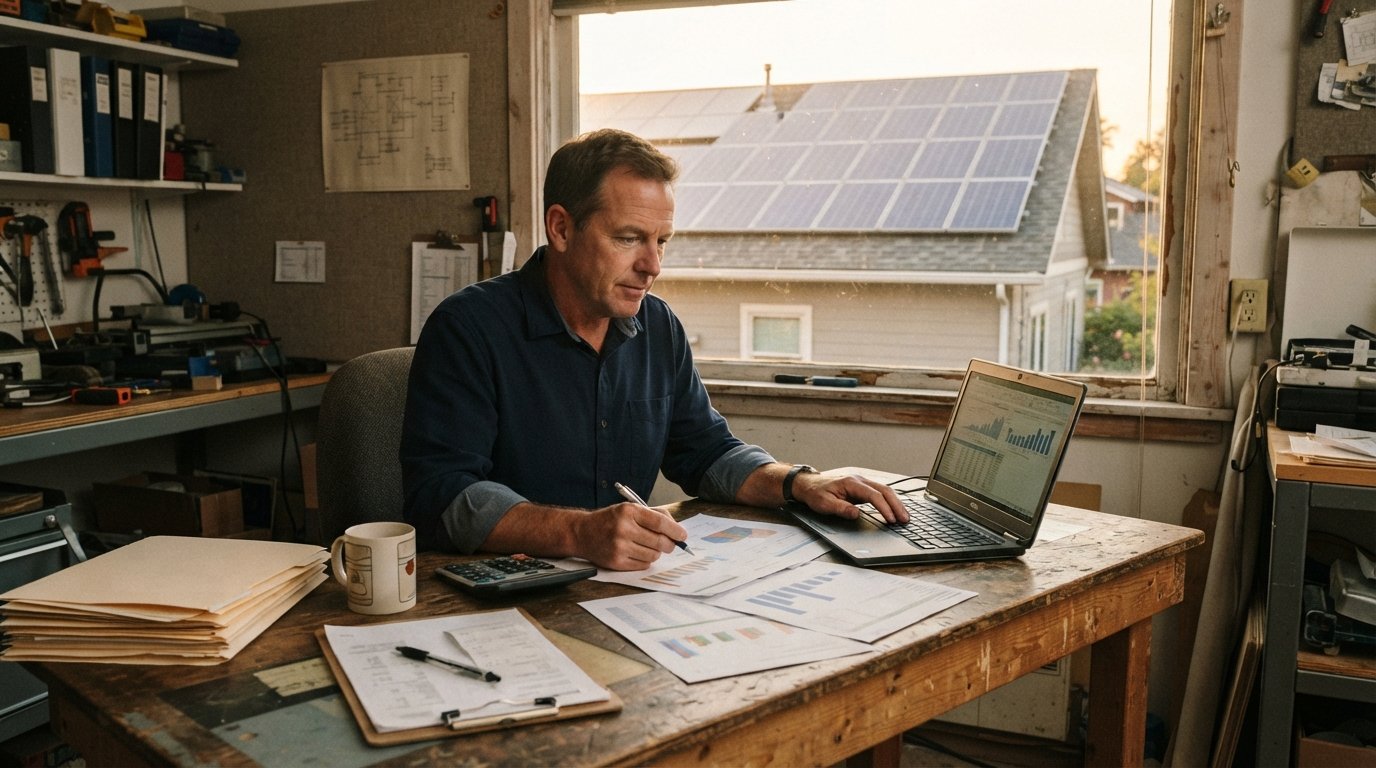
Solar for Small Business Tax Deductions and Write Offs
Solar for small business tax deductions and write offs can recover over half your system cost in year one. See how the ITC and depreciation stack.
By Andy Pearson
Learn more about Solar Panel Installation and Repair for guides, costs, and what to expect.
Compare Solar Panel Installation and Repair Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
Small business owners watch every dollar, and few expenses sting quite like a rising electric bill. If you have ever stared at a monthly utility statement and wondered whether there is a smarter way to power your operation, the federal tax code offers a genuinely compelling answer. Solar for small business tax deductions and write offs can turn a significant capital purchase into one of the most financially efficient moves your company makes this decade.
The opportunity is not a loophole or a gray area. Congress deliberately structured the tax code to reward businesses that invest in clean energy, and those rewards stack in ways that few other capital expenditures can match. Between the federal investment tax credit, accelerated depreciation through bonus depreciation, and the ability to deduct interest on financed systems, a small business can often recover a large share of its solar investment within the first year or two.
This guide walks through how each incentive works, how they combine, and what you need to know before you sign a contract. Whether you run a retail storefront, a machine shop, a dental office, or a small logistics company, the mechanics are similar, and the savings can be substantial.
How the Federal Solar Investment Tax Credit Works
The foundation of nearly every small business solar strategy is the federal Investment Tax Credit, commonly called the ITC. This is a dollar-for-dollar reduction of the federal income tax you owe, not merely a deduction that lowers taxable income. If your business owes $30,000 in federal taxes and claims a $30,000 credit, that liability drops to zero.
For systems placed in service in 2026, the credit generally covers 30 percent of the total installed cost of a solar system, including panels, inverters, racking, wiring, labor, permitting fees, and even certain site preparation costs. Battery storage added alongside the solar array can also qualify, which matters for businesses that want resilience against outages. The rules trace back to the Inflation Reduction Act, which extended and expanded these incentives for commercial projects.
One detail that trips up first-time buyers is the distinction between a tax credit and a tax deduction. A deduction reduces the income on which you are taxed, so a $10,000 deduction in a 24 percent bracket saves roughly $2,400. A $10,000 credit reduces the tax itself by the full $10,000. That difference is why the ITC is the centerpiece of solar for small business tax deductions and write offs planning.
Who Qualifies for the Commercial Solar ITC
Almost any for-profit business that owns its system or buys it through a qualifying financing arrangement can claim the credit. That includes sole proprietorships, partnerships, LLCs, S corporations, and C corporations. Businesses that lease their system from a third party generally cannot claim the ITC directly, because the leasing company claims it and passes along some benefit through lower lease payments.
Tax-exempt entities, including many nonprofits, cannot use the credit directly, but they may qualify for a direct pay option that converts the credit into a cash payment from the IRS. If your business falls into that category, it is worth speaking with a tax professional early, because the paperwork differs from a standard for-profit filing.
Bonus Depreciation: The Write Off That Supercharges Your Savings
If the ITC reduces your tax bill, depreciation write offs reduce your taxable income, and when the two are combined, the results can be dramatic. Solar equipment is classified as five-year property under the Modified Accelerated Cost Recovery System, which already allows faster write offs than the 39-year schedule applied to many building improvements.
Bonus depreciation allows businesses to deduct a large percentage of the system's cost in the first year it is placed in service, rather than spreading that deduction across five years. The exact percentage has shifted with recent tax legislation, and it is scheduled to phase down over time, so the year you install your system can materially affect your first-year deduction. A qualified tax advisor can tell you the current percentage and how it applies to your specific entity type.
Here is how the stacking typically works in practice. Suppose your business installs a $100,000 solar system and claims the 30 percent ITC, which equals $30,000. Your depreciable basis for the system is generally reduced by half the credit amount, so you would depreciate roughly $85,000. If bonus depreciation is available at a high percentage, you could write off most or all of that $85,000 in year one. Combined with the credit, the first-year tax benefit can approach or exceed half the system's sticker price for a profitable business.
It is important to note that depreciation deductions only help if your business has enough taxable income to absorb them. A startup with losses might carry the credit forward, but the timing of the benefit changes. This is one reason a conversation with your accountant before you sign an installation contract is so valuable.
State, Local, and Utility Incentives That Stack on Top
Federal incentives are the largest piece of the puzzle, but they are rarely the only piece. Many states offer their own tax credits, deductions, or property tax exemptions for commercial solar installations. Some states exempt the added value of a solar system from property tax assessments, which keeps your assessed value from climbing simply because you installed clean energy equipment.
Utility companies frequently layer on additional rebates or performance-based incentives. These vary widely by region and by program, and some are capped or reserved for specific customer classes. A manufacturing facility in one service territory might see a different rebate than a retail store in the same state, simply because the utility's program design differs.
Sales tax treatment also matters. Several states exempt solar equipment from sales tax entirely, which reduces the upfront cost that the ITC is calculated against. Because these rules change frequently, the most reliable approach is to verify current incentives with your state energy office, your utility, and a tax professional who works in your jurisdiction. The database of state incentives maintained by the federal government is a useful starting point, but it should never be the final word.
Financing Structures and Their Tax Consequences
How you pay for your solar system affects which write offs you can claim. The three common structures for small businesses are cash purchase, secured loan or equipment financing, and third-party ownership through a lease or power purchase agreement. Each has distinct tax implications.
A cash purchase gives you the clearest path to claiming the full ITC and all depreciation benefits, because you own the asset outright from day one. An equipment loan works similarly for tax purposes: you are treated as the owner, so you claim the credit and depreciation, and you can also deduct the interest paid on the loan as a business expense. That interest deduction is often overlooked, but over a multi-year loan it can add up.
Leases and power purchase agreements shift ownership to the third-party financier, which means that company claims the ITC and depreciation. In exchange, you typically pay a lower monthly rate or a per-kilowatt-hour price. This can be attractive for businesses that cannot use the tax credits, but for profitable companies with tax liability, ownership usually delivers the strongest economics.
- Cash purchase: full ITC, full depreciation, no interest deduction, highest upfront cost
- Equipment loan: full ITC, full depreciation, interest deduction, moderate upfront cost
- Lease or PPA: no ITC or depreciation for your business, lower monthly payments, no ownership
Before choosing a structure, model your tax situation for the next three to five years. A business expecting strong profits will generally benefit most from ownership, while a business with volatile income or no tax liability might prefer a third-party arrangement. If you are still sizing your system, our guide on solar system sizing for small homes explains how load calculations work, and the same principles apply to small commercial spaces.
Common Mistakes That Cost Small Businesses Money
The rules are generous, but they are not automatic. Businesses lose value every year because of avoidable errors in how they document, time, or structure their solar investment. Understanding these pitfalls before you buy can preserve thousands of dollars in benefits.
One frequent mistake is claiming the ITC on a system that is not yet placed in service. The credit applies in the tax year the system is operational, not the year you sign the contract or pay a deposit. If your installation slips from December to January, your credit shifts to the following year, which can matter if your tax situation is changing.
Another common error is failing to keep adequate records. The IRS expects documentation of total system cost, including invoices, permits, and proof of payment. Businesses that commingle solar expenses with general construction or renovation costs can find themselves unable to substantiate the credit if questioned. A separate cost breakdown from your installer is worth requesting before the project begins.
Finally, many owners overlook the interaction between the ITC and state grants. In some cases, a state rebate reduces the federal basis, which lowers the credit. In others, it does not. The rules are specific, and assuming they work one way when they work another can lead to an unpleasant surprise at filing time.
Realistic Payback and Return on Investment
When you combine the ITC, bonus depreciation, state incentives, and avoided electricity costs, the economics of commercial solar can be compelling. Many small businesses see simple payback periods in the range of four to seven years, depending on local electricity rates, system size, and how aggressively they can use the tax benefits. After payback, the system continues producing power for decades with minimal maintenance.
The return on investment often compares favorably to other uses of capital, particularly for businesses with high electricity consumption during daylight hours. A refrigeration-heavy grocery, a machine shop running daytime shifts, or an office with significant air conditioning load can offset a large share of its usage directly, which improves the math considerably compared to exporting power to the grid at wholesale rates.
Because every business has a different load profile and tax position, generic payback estimates only go so far. The most reliable approach is to gather multiple quotes, review them with your accountant, and model the after-tax cash flow. Platforms like SolarEnergy.ai provide educational resources and tools that can help you sanity-check installer proposals before you commit. If you want to compare vetted local installers side by side, requesting quotes through a reputable matching service is a practical first step.
Steps to Claim Your Solar Tax Benefits
Claiming solar for small business tax deductions and write offs is not complicated, but it does require coordination between you, your installer, and your tax professional. Following a clear sequence reduces the risk of missing a benefit or triggering an audit flag.
- Confirm your tax position: verify you have or expect enough liability to use the credit, and discuss timing with your accountant.
- Get itemized quotes: ask installers to break out equipment, labor, permits, and storage costs separately.
- Document everything: keep invoices, contracts, proof of payment, and utility interconnection approvals in a dedicated folder.
- Place the system in service: ensure installation and utility approval are complete before the tax year closes if you want the credit that year.
- File the correct forms: work with your tax preparer to claim the ITC and depreciation on the appropriate returns.
Each step builds on the last, and skipping one can delay or reduce your benefit. The businesses that capture the full value of these incentives tend to be the ones that treat the tax planning as part of the project, not an afterthought once the panels are on the roof.
Solar for small business tax deductions and write offs reward owners who plan ahead. The combination of a 30 percent federal credit, accelerated depreciation, and state or utility incentives can transform a solar installation from a significant expense into one of the best-performing capital decisions your company makes. Start with a clear picture of your tax situation, gather transparent quotes, and keep thorough records. Do that, and the numbers have a way of making the decision for you.