
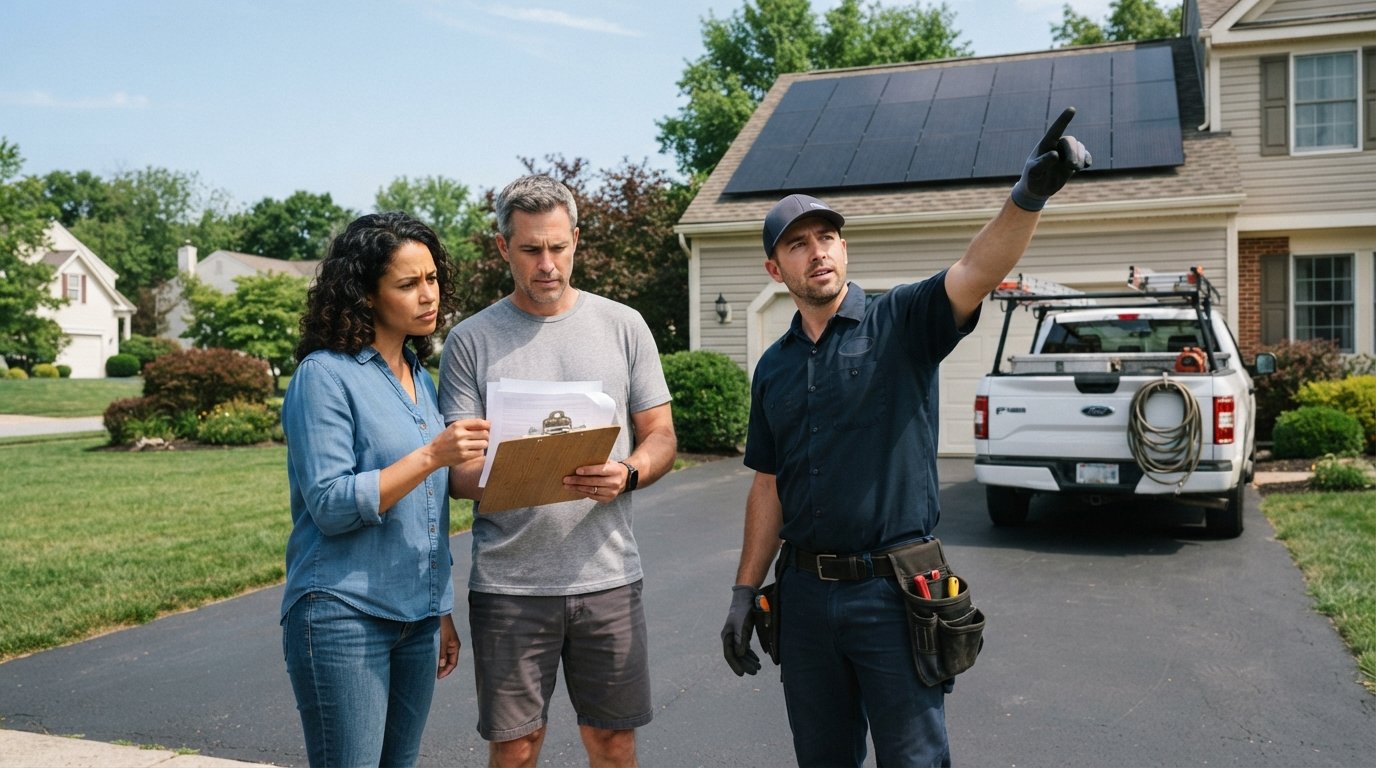
Solar Leasing Pros and Cons for Homeowners in 2026
Solar leasing pros and cons for homeowners in 2026, plus a simple framework to decide. Call 8332123715 for expert guidance.
By Alex Carter
Find Local Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
Solar leasing has become one of the most talked-about ways to go solar without a large upfront payment. But in 2026, the math looks different than it did just a few years ago. Falling equipment prices, new battery incentives, and changing utility rules have reshaped the decision. If you are a homeowner weighing a lease against buying a system outright, the stakes are real: a typical 25-year lease can mean tens of thousands of dollars paid over time, and the fine print can affect everything from your roof repairs to your home sale.
This guide breaks down the solar leasing pros and cons for homeowners in 2026 in plain language, with real numbers, contract traps to watch, and a simple framework for deciding whether a lease, a power purchase agreement, or full ownership fits your situation. By the end, you will know exactly which questions to ask before signing anything.
How Solar Leasing Works in 2026
A solar lease is a financing arrangement in which a third-party company owns the solar panel system installed on your roof, and you pay a fixed monthly amount to use the electricity it produces. You do not buy the equipment. You do not claim the federal tax credit. You simply pay for the power, usually at a rate that starts below your utility's retail rate and then rises each year by a set escalator, often between 1 percent and 3 percent.
A solar power purchase agreement, or PPA, works almost identically, except you pay per kilowatt-hour of electricity produced rather than a flat monthly fee. Both structures are considered third-party ownership, and both come with the same core trade-off: little or no money down in exchange for giving up ownership, tax benefits, and some control over your roof and your home sale.
In 2026, the landscape has shifted in several important ways. Residential solar equipment costs have continued to fall, which means the gap between leasing and buying has narrowed. At the same time, many states have revised net metering policies, reducing the credit you get for exporting excess power to the grid. That change makes battery storage more valuable, and it also makes it more important to understand who owns the battery in a lease deal. Some leases now bundle a battery; many do not. If you want a deeper look at how PPAs compare, our guide on solar PPA for homeowners walks through the contract mechanics step by step.
The bottom line is that leasing remains a legitimate option, especially for homeowners who cannot use the federal tax credit or who want predictable payments without maintenance headaches. But the details matter more than ever, and the wrong contract can cost you far more than the right one.
The Strongest Pros of Solar Leasing
The appeal of leasing is straightforward: it removes the biggest barrier to going solar, which is the upfront cost. A typical residential system in 2026 costs between $18,000 and $30,000 before incentives, depending on size, roof complexity, and local labor rates. A lease turns that into a monthly payment that often starts lower than your current electric bill.
Here are the main advantages homeowners cite when they choose a lease:
- No upfront cost: Most leases require $0 down, so you can go solar without touching savings or taking on a loan.
- Predictable payments: Your monthly lease payment is fixed, with a known escalator, which makes budgeting easier than volatile utility rates.
- Maintenance included: The leasing company typically handles monitoring, repairs, and inverter replacement for the life of the agreement.
- No tax credit needed: If your tax liability is low, you do not lose anything by letting the leasing company claim the federal credit.
- Performance guarantees: Most contracts include a production guarantee, so you are compensated if the system underperforms.
There is also a cash-flow argument that many homeowners find compelling. If your lease payment is $110 per month and your old electric bill averaged $180, you are saving $70 per month from day one, with no capital outlay. Over a year, that is $840 back in your pocket, and the savings continue as long as utility rates rise faster than your lease escalator.
For homeowners who plan to stay in the home for the full lease term and who value simplicity over maximum long-term return, leasing can be a genuinely good deal. It is not the cheapest way to go solar over 25 years, but it is often the easiest.
The Real Cons of Solar Leasing
The drawbacks of leasing are less obvious at the sales table but become clear over time. The biggest one is total cost. Because the leasing company owns the system, it captures the federal tax credit, any state incentives, and the long-term value of the electricity. You get the savings, but you do not get the asset.
Consider the numbers. A leased system might cost you $40,000 to $60,000 in total payments over 25 years, depending on the escalator. Buying the same system with a loan might cost $28,000 to $35,000 after incentives, and once the loan is paid off, your power is essentially free. That difference, often $15,000 or more, is the price of convenience.
Other significant cons include:
- Home sale complications: A lease must be transferred to the buyer, and some buyers refuse to take on the obligation. This can delay or kill a sale.
- Roof and remodel constraints: Removing and reinstalling panels for a new roof can cost $1,500 to $4,000, and the lease company controls the schedule.
- Escalating payments: A 2.9 percent annual escalator can raise a $100 payment to nearly $200 over 25 years, eroding your savings.
- No ownership asset: You build no equity, and the system does not increase your home value the way an owned system often does.
- Lien on the home: Many leases place a UCC-1 fixture filing on the property, which can complicate refinancing.
There is also the question of flexibility. If you want to add panels later, install a battery, or change your energy usage, you generally need the leasing company's approval. Some contracts make upgrades difficult or expensive. And if you sell the home, the buyer must qualify for the lease transfer, which adds a credit check and paperwork to an already stressful process.
None of these cons make leasing a bad choice in every case. They simply mean you should read the contract carefully and compare the total cost of leasing against buying before you commit.
Solar Lease vs Buying: A Side-by-Side Comparison
The clearest way to decide is to compare the two options across the factors that matter most: upfront cost, lifetime cost, tax benefits, maintenance, home sale impact, and flexibility. The table below summarizes how they stack up in 2026.
- Upfront cost: Lease $0; Buy $0 to $30,000 depending on loan or cash.
- Lifetime cost: Lease often $40,000 to $60,000; Buy often $28,000 to $35,000 after incentives.
- Federal tax credit: Lease goes to the company; Buy goes to you.
- Maintenance: Lease included; Buy your responsibility, though panels are low-maintenance.
- Home sale: Lease must transfer; Buy transfers automatically with the home.
- Flexibility: Lease limited; Buy full control over upgrades and timing.
If you plan to move within five to seven years, a lease can be a liability because the transfer requirement may scare off buyers. If you plan to stay long term and you can use the tax credit, buying almost always wins on total cost. If you cannot use the tax credit and you want zero risk, a lease can still make sense.
One middle path worth considering is a solar loan. You own the system, you claim the tax credit, and you pay a fixed monthly amount that is often similar to a lease payment. The difference is that you build equity and you keep the savings after the loan is paid off. For many homeowners in 2026, a loan offers the best of both worlds.
If you want to estimate your own numbers, a good starting point is to gather three quotes for an owned system and one lease quote, then compare the 25-year totals side by side. You can also use an independent solar savings calculator to sanity-check the production estimates and utility rate assumptions you are given. For broader industry data and tools, SolarEnergy.ai is a useful resource for comparing technology trends and incentive updates.
Contract Traps to Watch Before You Sign
Most lease problems trace back to the contract, not the technology. Sales presentations tend to focus on the monthly payment and the savings estimate, while the fine print governs what happens when life does not go as planned. Before you sign, read the agreement with a highlighter and pay attention to these clauses.
The first is the escalator. A lease with a 0.9 percent annual increase is very different from one with a 2.9 percent increase. Over 25 years, that difference can add $10,000 or more to your total cost. Ask for the total of all payments over the full term, in writing, and compare it to the total you would pay for an owned system.
The second is the transfer clause. Some leases require the buyer to qualify based on credit score and income. Others allow the company to demand a lump-sum buyout if the buyer does not qualify. Know exactly what happens if you sell, and ask whether you can prepay or buy out the lease early without a penalty.
The third is the roof and removal clause. If you need a new roof, who pays to remove and reinstall the panels, and how long will it take? Typical costs run $1,500 to $4,000, and some contracts put that burden on the homeowner. If your roof is more than 10 years old, this is a serious consideration.
Finally, check the production guarantee and the monitoring terms. A good guarantee compensates you if the system produces less than promised, but the compensation formula matters. Some pay at the retail rate; others pay at a lower avoided-cost rate. Read the details and ask for a sample calculation.
Who Should Lease and Who Should Buy in 2026
Leasing is not universally good or bad. It fits a specific profile. You should seriously consider a lease if you cannot use the federal tax credit, if you have a low credit score that makes a loan expensive, if you want zero maintenance responsibility, or if you plan to stay in the home for the full 25-year term and value predictable payments over maximum savings.
Buying, whether with cash or a loan, is usually the better choice if you can claim the tax credit, if you plan to stay long term, if you want to maximize your return, or if you may sell within a few years and do not want a transfer obligation hanging over the sale. Owning also gives you control over upgrades, including adding a battery later as net metering rules continue to change.
A practical way to decide is to run three scenarios: cash purchase, loan, and lease. Compare the 25-year total cost, the monthly payment, and the exit flexibility. In most cases, the lease will have the lowest upfront cost and the highest lifetime cost. The question is whether the convenience is worth the premium for your situation.
Whatever you choose, get multiple quotes. Pricing and contract terms vary widely between installers and leasing companies, and the difference between a fair deal and a poor one often comes down to the escalator, the transfer clause, and the buyout terms. A few hours of comparison can save you thousands of dollars.
Solar leasing pros and cons for homeowners in 2026 come down to a simple trade-off: you give up ownership and long-term savings in exchange for zero upfront cost and a hands-off experience. If that trade fits your finances and your timeline, a lease can be a smart move. If you can afford to own, the numbers usually favor buying. Either way, read the contract, compare the totals, and make the choice that matches how long you plan to stay in your home.